October 28, 2026:In the night session on October 27, coking coal’s front-month contract JM2701 settled at 1,430.5 yuan/t, up 3.17%, the top gainer across the market. Coke rose 2.43% to 1,938 yuan/t. Rebar added only 0.66% to 3,046 yuan/t, hot-rolled coil was up 0.13% at 3,172 yuan/t, and iron ore edged 0.08% lower. Input costs are moving faster than finished-steel prices.
Coking coal had fallen more than 7% over the previous two weeks on expectations that idled Shanxi mines would resume output. The rebound follows two supply-side events:
Mongolia: The operator of the 477km Tavan Tolgoi–Mandal–Khangi coal road halted traffic from 19:00 on October 15, after a state inspection found maintenance and safety conditions for 2025–26 below standard. The route feeds China’s Mandula port, which was clearing roughly 500 trucks/day, of which fewer than 60 carried Mongolia No. 5 raw coking coal. The larger Ganqimaodu corridor, running above 710 trucks/day, is unaffected.
Domestic output: The 30 largest coking-coal producers averaged 535,000 t/day in mid-October, up 4.1% on the first ten days but still 3.9% below a year earlier.
Galaxy Futures noted that Shanxi restarts are still building and the Khangi route is due to resume gradually from November. With hot metal output at 247 sample mills at 2.323m t/day and mill profitability at 11.26%, the demand side offers limited support. The move looks like a correction of an over-extended short position rather than a new upward trend.
A Jieyang (Guangdong) mill has idled its blast furnace for about 20 days of maintenance, with the whole plant temporarily shut. The stoppage is expected to cut roughly 60,000 tonnes from monthly output; the mill supplies Guangzhou, Jieyang and Quanzhou, and on-site inventories are already thin. It follows similar outages at Anyang Yaxin in Henan and Ningxia Jianlong, pointing to a broader reduction in supply rather than isolated maintenance.
In Shandong, the premium of coiled rebar over conventional rebar has widened to 200 yuan/t, its highest since mid-2024, after spending most of the past three years between 150 and 180 yuan/t. Local long-product operating rates are low, while coiled rebar demand from infrastructure and prefabrication has held up better.
Baosteel (600019.SH) reported after the bell on October 27:
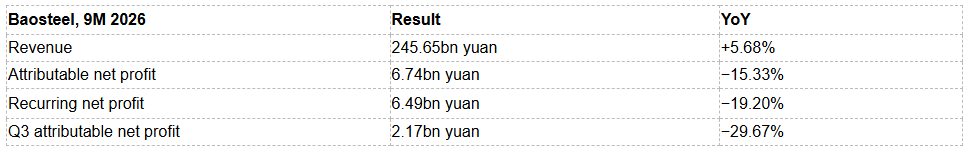
The company cited a narrower gap between steel selling prices and input costs. Lvliang premium hard coking coal was up 34.9% in Q3 versus Q2, while Platts 62% iron ore fell 7.9%; the China Steel Association price index slipped 1.9% in the quarter.
Sector-wide, National Bureau of Statistics data show profit at ferrous metal smelting and rolling at 24.34bn yuan for January–September, down 73.3% YoY. Results are mixed elsewhere: Xinxing Ductile Iron Pipes posted 444m yuan in nine-month profit, Jiuli Hi-Tech about 453m yuan, and Baotou Steel roughly 172m yuan in Q3.
Outlook:
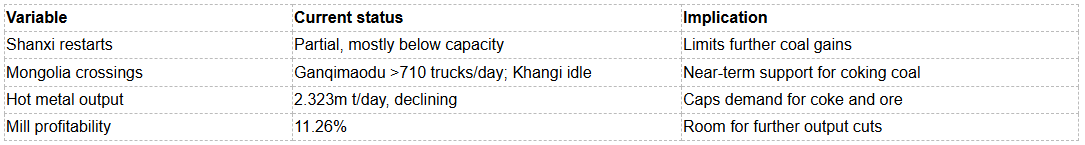
Industrial profits at China’s designated-size enterprises rose 15.5% in January–September; all 31 provinces posted positive GDP growth. The gains are not reaching steelmakers, where input costs, local supply shortages and realised margins are moving in different directions.
Sources: exchange settlement data, Mysteel, China Coal Transport and Sales Association, National Bureau of Statistics, company filings. For information only, not investment advice.